

Here’s something that bothered me for a long time.
Many billionaires, millionaires, financial celebrities and people with a net worth that ends in 7 or more zeros, they all often say the same thing when someone points a camera at them.
“Just buy index funds.”
Warren Buffett, one of the wealthiest people in the world says it, Former NBA owner Mark Cuban says it, and many guests on most financial podcasts eventually gets there.
I used to take that at face value until I started paying attention to what they actually did, not what they said.
The Billionaire Lie
“Buy index funds” is the most repeated piece of investment advice in the world.
Here’s what none of them lead with.
Jeremy Schneider is the guy behind Personal Finance Club, the account with 400,000+ followers preaching index funds, yet he didn’t get rich from index funds.
He built a company called RentLinx in his twenties, paid himself a modest $36,000 salary while he grew it, and sold it for $5 million at 34.
The index fund investing was happening quietly in the background the entire time. The real wealth event was owning and selling a business he built.
Matt Kaplan, founder of ACE Entertainment which is the production company behind Netflix hits like To All the Boys I’ve Loved Before, didn’t build his wealth investing in index funds. He built it producing films and owning equity in the company that made them.
Even the founder in Moneywise’s anonymous interview series who sold his business for $80 million put it plainly
I’d always had a little bit of money in index funds, but I never would put a big chunk in there, because the risk part is my business.
They built wealth through ownership, a company, equity, real assets they controlled and understood. Once the money existed, they moved a portion into index funds to protect it while still receiving dividend/interest payouts. This strategy is considered preservation.
The Two-Phase Playbook Nobody Talks About
There’s a framework investors actually use, even if they don’t describe it this way publicly. Researchers call it the core-satellite strategy.
The “core” is passive: low-cost index funds that track the market and will more than likely hold value steadily over time. The “satellites” are high-conviction positions in individual stocks, real estate, or sector-specific plays designed to outperform the market.
The data backs this up plainly. Concentrated, conviction-based investments create fortunes. Index funds preserve them. So when you are working your way up as a small business owner it’s smart to split your savings with these two styles of investments.
What the S&P 500 Actually Does
Index funds are genuinely good. I’m not here to trash them. The S&P 500 has delivered an average annual return of roughly 10% since inception. Over the last 10 years, that number climbs to about 15.6%. That’s real, compounding wealth.
But here’s what the averages hide.
Year S&P Index Return
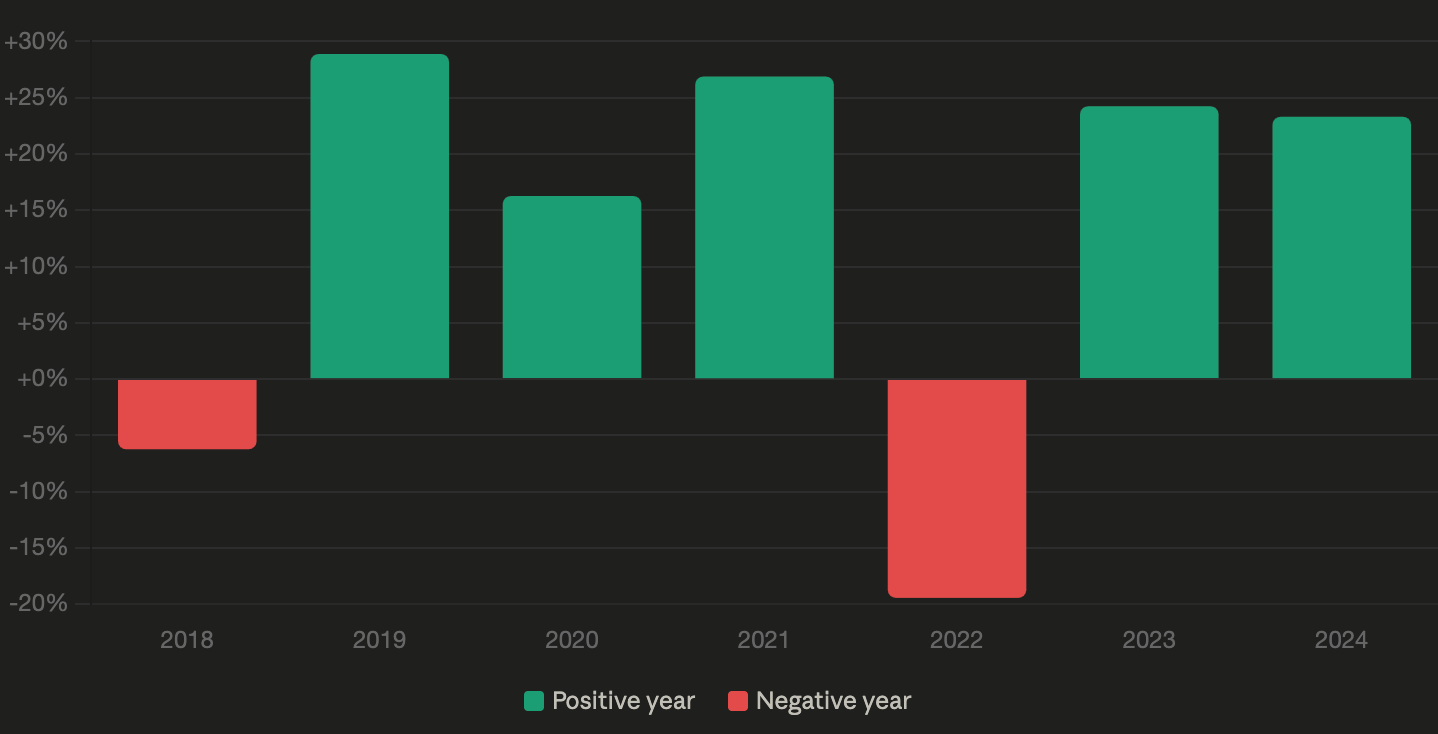
The “average” of around 15% almost never actually happens in a given year. You’re either up big or dealing with a real drawdown.
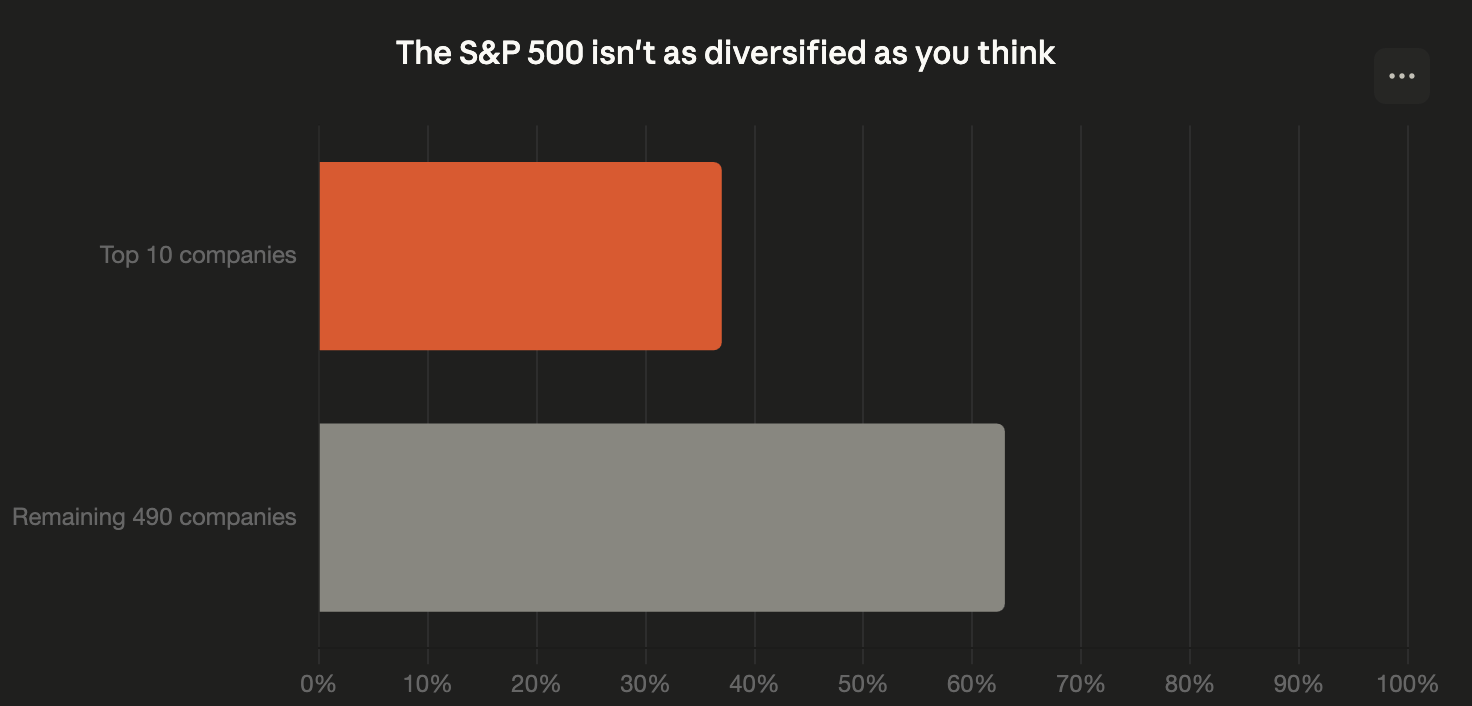
When you buy an index fund today, you’re not buying the diversified product your parents invested in. You’re buying a product heavily weighted toward mega-cap tech.
If you’re going to have concentration risk anyway, the question becomes whose concentrated bets do you want to ride?
Gene After Hours is a newsletter about the financial and business side of building a life that compounds as a creative, the part nobody teaches you in school.
Subscribe below to get the next issue when it drops.
What I’ve been doing to weather any economic environment
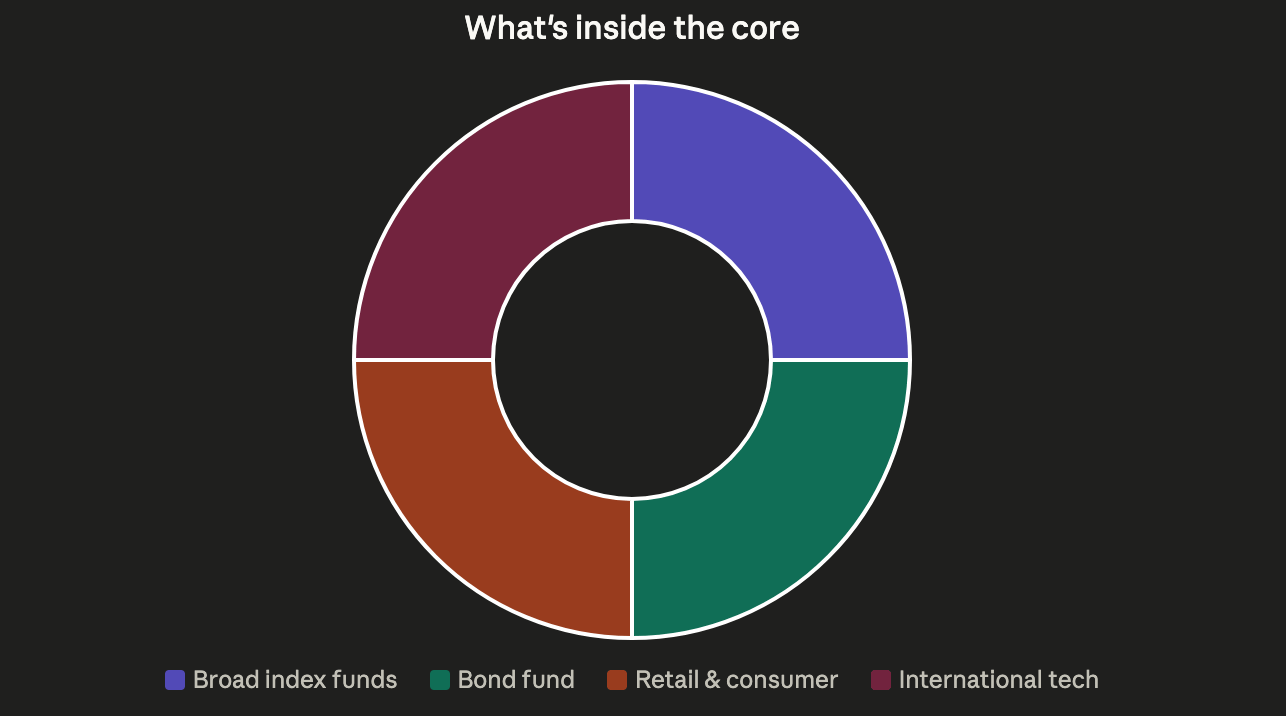
My core is the steady, boring engine. It’s money that goes in every month with the intention to never be touched until retirement. It’s split across a few different fund types inside a SEP IRA and Self Employed 401k. None of this requires me to think hard or check it daily. That’s the point.
My satellite portfolio is an account where you keep high conviction stock investments. I keep it in a separate account on purpose, so I can clearly see how it’s performing against my core without the numbers blending together. Right now I hold 13 individual companies I have high conviction in.
Here’s what high conviction actually looks like with real numbers.
In 2022, I bought Palantir at $13-14 a share. A $5,000 investment has grown to roughly $60,000.
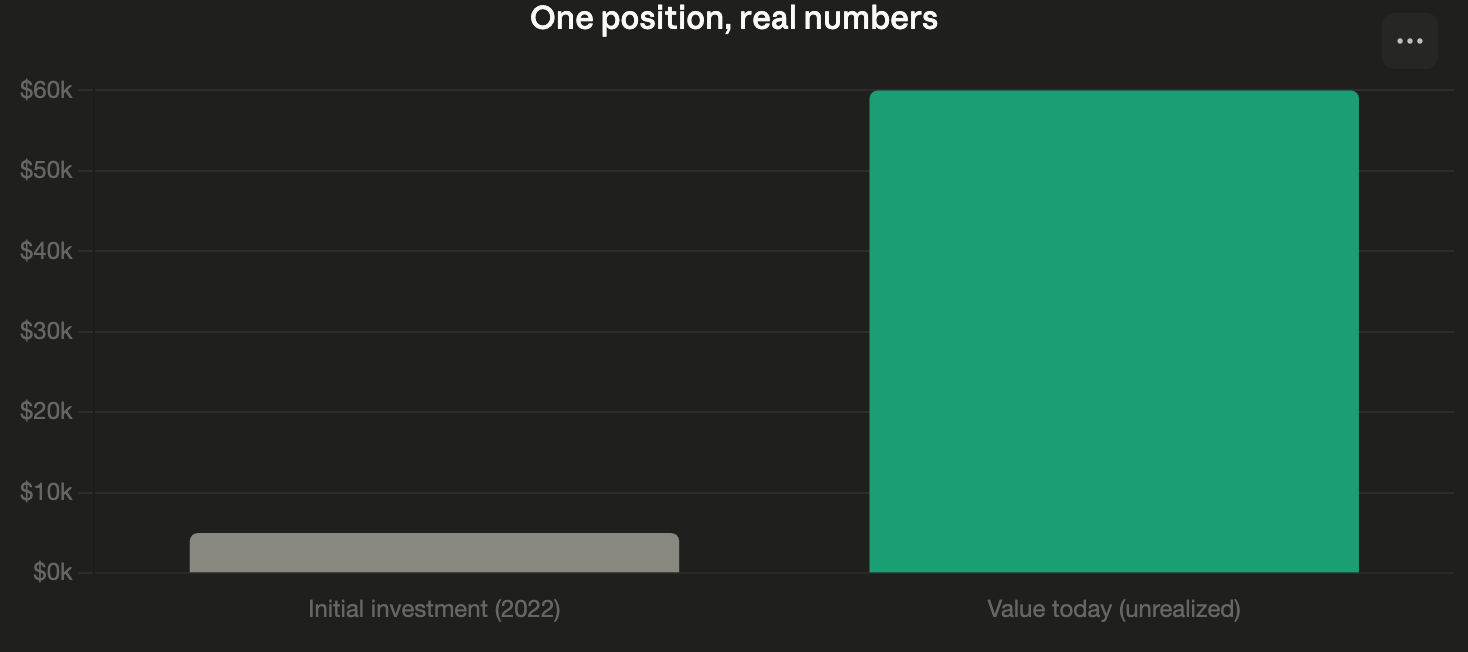
That money is unrealized until I actually sell, but it’s real on paper. That’s the kind of return that never happens just matching the index, it happens from understanding a company well enough to buy it early or at a time it was undervalued and hold through the noise instead of panic-selling.
How often does this occur?
Not every position works out that way and that’s okay! It’s investing!
Let’s compare it to when you buy camera gear or buy a computer. When you buy it it could take 1 month or 1 year for you to make enough money to get your return on investment.
It’s the same concept. A $5,000 investment that is down 50% doesn’t mean it’s a loss. It simply means your investment hasn’t matured yet. Did the business fail? Did they switch services? Are they selling their business? If the core reason for you buying into the company didn’t change why worry?
Capital Tax Rate
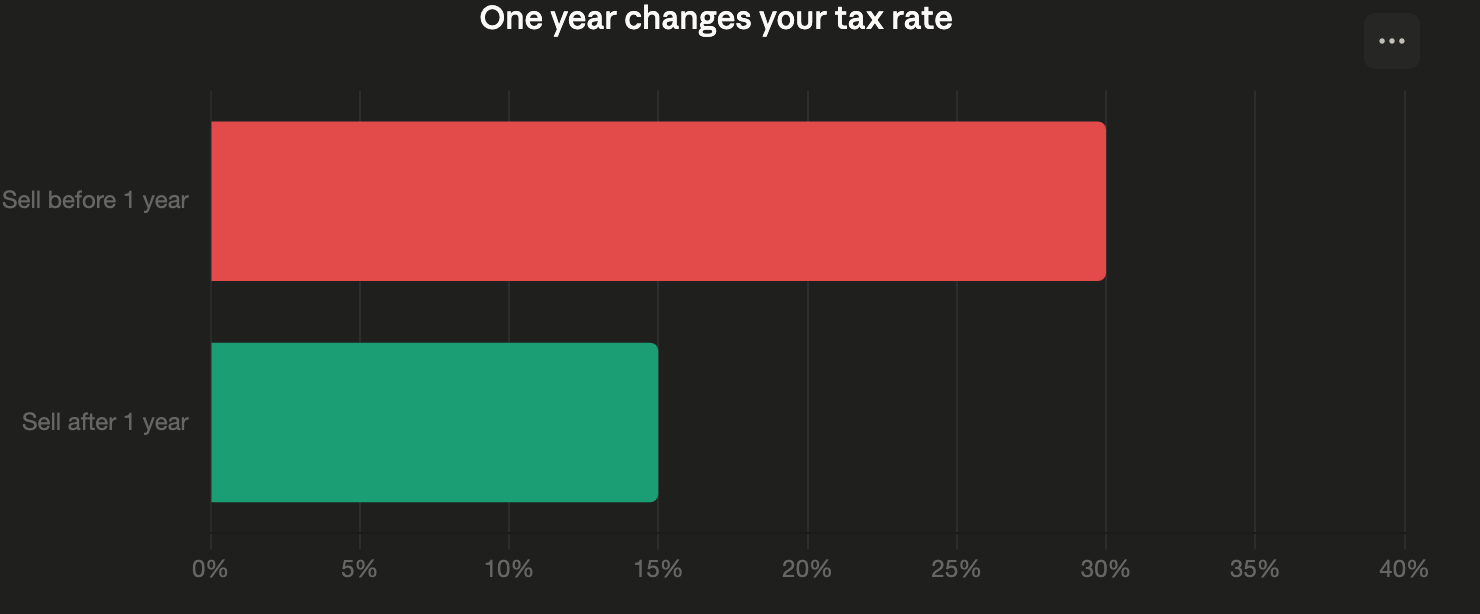
Two things worth knowing if you ever sell a winning position.
If you hold it for over a year before selling, your tax rate drops significantly. Sell before a year and it’s taxed as regular income, often 30% or more. Hold past the one-year mark and it becomes a long-term capital gain, which can drop to 15% or even lower depending on your tax bracket.
Don’t sell it unless you have to. I’ve sold a partial winning position to allocate to a new high conviction investment. I still have a large portion of my original investment profits while not missing out on another opportunity.
Talent creates income. Ownership creates freedom.
Gene